
Finance Minister Muhammad Aurangzeb told an audience in Singapore this week that Pakistan will nearly double lending to small and medium enterprises, to Rs2 trillion by June 2028. The promise is easy to state. The arithmetic behind it is harder: at the pace of the last three months, lending must grow more than five times faster, and the number of borrowers about two and a half times faster, for the target to be met.
The numbers behind the promise
Small firms dominate Pakistan’s economy. Aurangzeb told the Global SME Finance Forum 2026 in Singapore on 18 November that they make up 90 percent of businesses, contribute 40 percent of GDP, generate about 20 percent of exports and provide roughly 78 percent of non-farm employment. Yet formal bank credit barely reaches them. Outstanding SME financing stood at Rs1.137 trillion at the end of September 2026, according to the Finance Division, up only Rs23 billion from Rs1.114 trillion in June. Borrowers rose by more than 25,000 to about 350,862 in the same period. The latest reading: the Finance Ministry put financing at Rs1.148 trillion by 23 October, including Rs538 billion for small enterprises. Small firms’ share of domestic private advances was 9.90 percent in August, and the government wants it at 13 percent by June 2028. The prime minister has separately spoken of Rs2.2 trillion for the same date.
The pace gap
That is where the promise meets its hardest test. The gap between Rs1.137 trillion and Rs2 trillion is Rs863 billion. Spread over the 21 months to June 2028, that means adding about Rs41 billion of outstanding financing every month. The last three months added about Rs7.7 billion a month, so the monthly pace must rise more than five times and stay there for almost two years. The borrower arithmetic is only slightly kinder: reaching 775,000 borrowers from 350,862 means adding about 424,000 firms, or roughly 20,200 a month, against about 8,300 a month in the last quarter. The State Bank has set an intermediate target of Rs1.5 trillion by June 2027, the first real checkpoint. These are outstanding balances, net of repayments, so every rupee repaid must be replaced before the total can grow.
The three tools meant to close it
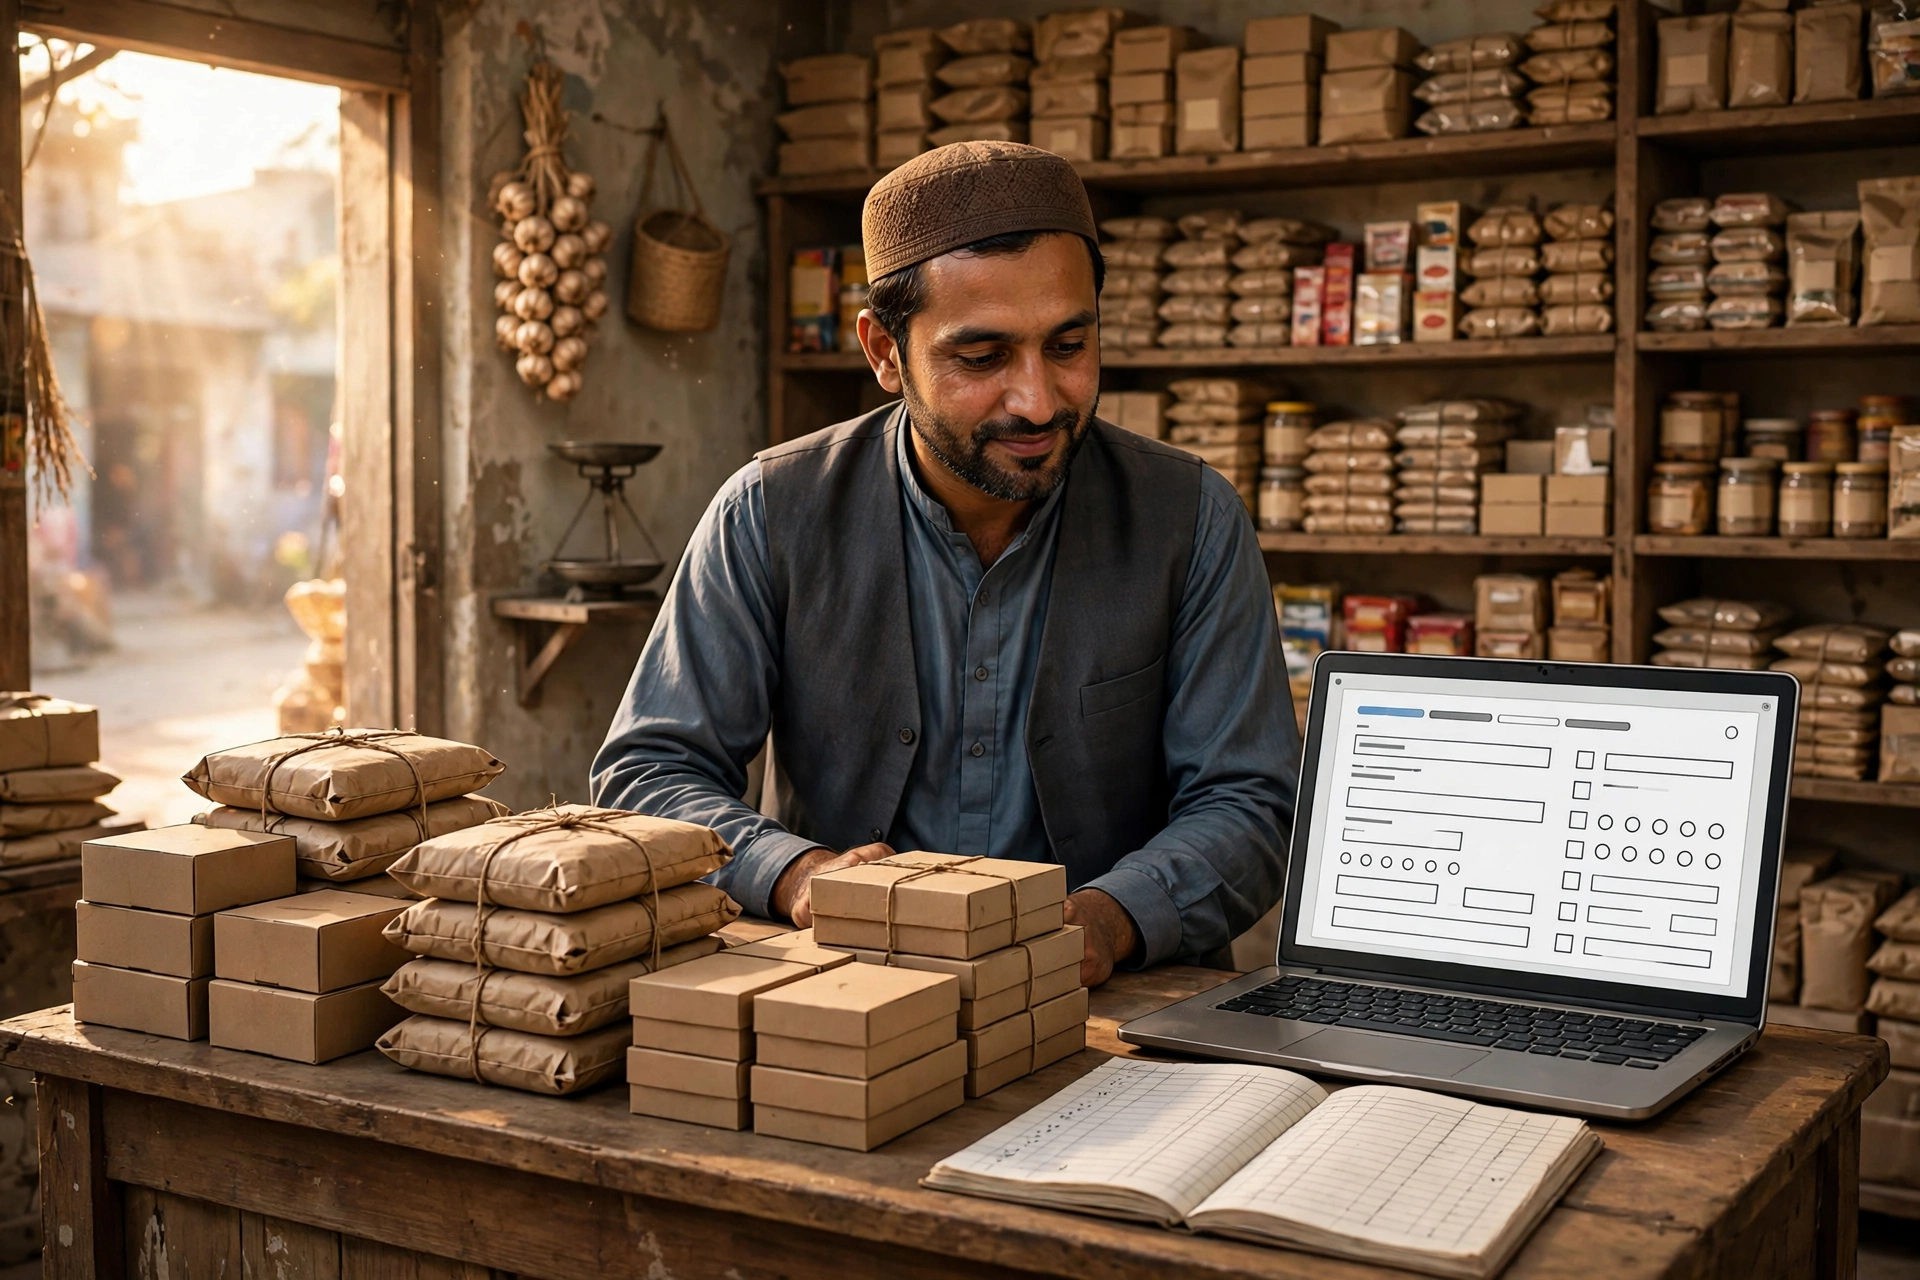
The government is betting on three changes. First, the State Bank’s SME Connect Portal, launched on 1 November, lets small firms register, apply and track applications, and publishes banks’ processing times. Second, the Export Finance Scheme has been raised from Rs1 trillion to Rs1.5 trillion, with Rs300 billion set aside for small and medium exporters and new exporters, and SME exporters offered financing at a 6 percent end-user interest rate. Third, the finance minister wants lending to move beyond collateral, using digital payments, alternative credit checks and risk-sharing so firms without property to pledge can still borrow. The Small and Medium Enterprises Development Authority is running financial literacy programmes and help desks, and signed agreements with the Institute of Cost and Management Accountants of Pakistan and the digital bookkeeping platform DigiKhata on 5 November to improve small firms’ records. For exporters, the USD to PKR exchange rate today decides what their earnings are worth.
Why banks have stayed away
A 2024 comparison by PwC Pakistan shows how far behind the region Pakistan sits: small firms receive 3.7 percent of total bank advances here, against 16 percent in India, 19 percent in Bangladesh, 20 percent in Indonesia and 23 percent in Kenya. Collateral-based lending is the main reason. A shopkeeper with no property to pledge and no audited books has little to offer a bank’s credit committee, however sound the business. That is why the minister’s focus on digital lending matters: if alternative credit checks work, the pool of lendable firms grows without waiting for property titles. One cost has already eased: petrol fell to Rs322 a litre in the twelfth straight cut this week, trimming transport bills for small firms that move goods by road. The State Bank’s annual report gives the central bank’s own picture of where credit in the economy is flowing, and where it is not.
What to watch next
The test of the promise will come in the monthly figures, not in speeches. The finance minister has demanded bank-wise plans, and the Access to Finance Steering Committee reviews progress regularly. Three markers matter most: whether the SME Connect Portal starts publishing bank processing times and complaints, whether the Rs300 billion in the Export Finance Scheme reaches new exporters rather than existing ones, and whether the September quarter’s Rs23 billion addition starts climbing towards Rs40 billion a month. If the pace stays where it is, Rs2 trillion will still be more than Rs700 billion away when June 2028 arrives. For more business and economy news from Pakistan, follow our coverage.